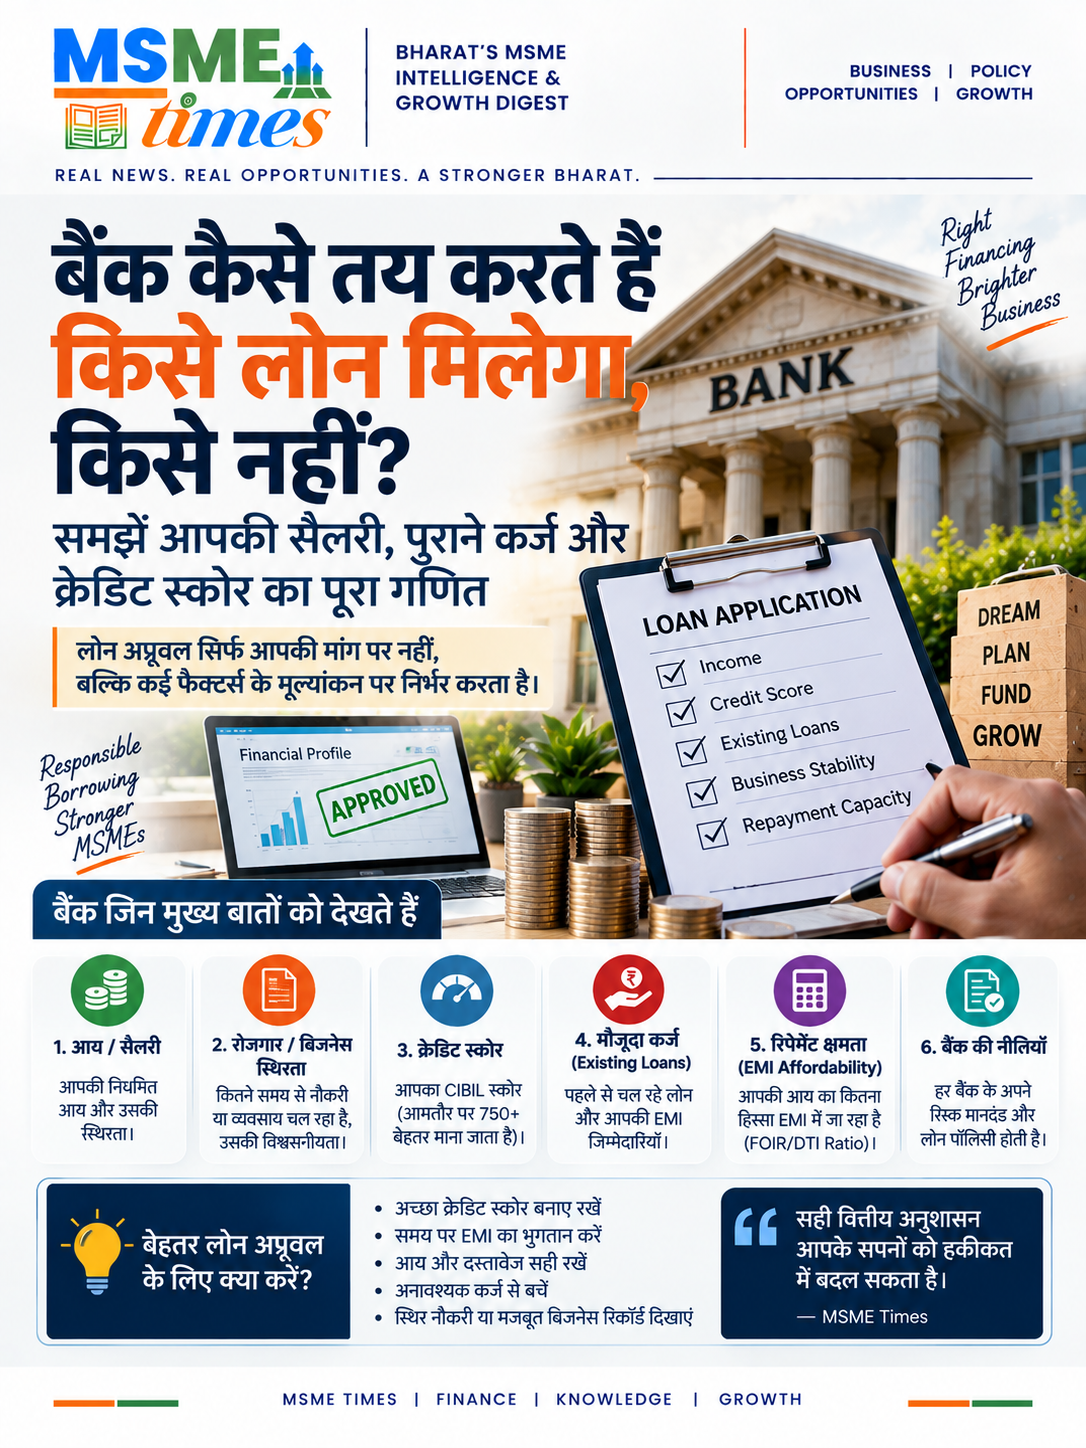
Bank Loan Approval: बैंक कैसे तय करते हैं किसे लोन मिलेगा और किसे नहीं?
Bank loan approval सिर्फ आपकी सैलरी देखकर नहीं होता। बैंक और lenders loan application को approve करने से पहले borrower की income, employment status, credit history, existing loans, repayment capacity और कई अन्य factors का मूल्यांकन करते हैं। TransUnion CIBIL के अनुसार, lenders loan application के दौरान CIBIL Score और credit report की जांच करते हैं।
यही वजह है कि अच्छी salary होने के बावजूद किसी व्यक्ति को कम loan amount मिल सकता है या application reject हो सकती है।
Bank Loan Approval में सबसे पहले क्या देखा जाता है?
हर bank की policy और loan product अलग हो सकता है, लेकिन कुछ broad factors लगभग हर lending decision में महत्वपूर्ण होते हैं।
1. Income और Salary
आपकी monthly income यह निर्धारित करने में महत्वपूर्ण भूमिका निभाती है कि आप कितना loan comfortably repay कर सकते हैं।
Bank आम तौर पर salary slips, bank statements और अन्य income documents देख सकता है।
सिर्फ ज्यादा salary होना पर्याप्त नहीं है। Bank यह भी देखता है कि आपकी income के मुकाबले आपकी existing financial commitments कितनी हैं।
2. CIBIL Score और Credit History
Bank loan approval में credit score महत्वपूर्ण factors में से एक है।
TransUnion CIBIL के अनुसार, lenders CIBIL Score और Report का उपयोग borrower की credit history और creditworthiness का मूल्यांकन करने के लिए करते हैं। Higher credit score loan approval की संभावना को बेहतर बना सकता है।
Credit report में payment history, overdue amounts और existing credit facilities जैसी जानकारी भी देखी जाती है।
Credit score कम होने पर क्या होता है?
कम score होने पर lender:
- loan application reject कर सकता है
- कम amount approve कर सकता है
- higher interest rate offer कर सकता है
- additional documents मांग सकता है
यह lender और loan product की policy पर निर्भर करता है।
3. Existing Loans और पुराने कर्ज
अगर आपके ऊपर पहले से कई loans हैं, तो bank यह देखेगा कि नई EMI आपके existing financial commitments के साथ manageable है या नहीं।
मान लीजिए आपकी salary ₹60,000 है और पहले से home loan, car loan और credit-card EMI चल रही है। ऐसे में आपकी पूरी salary नई EMI के लिए available नहीं है।
इसीलिए existing debt bank loan approval में महत्वपूर्ण भूमिका निभाता है।
4. EMI-to-Income Ratio
Bank यह भी देखता है कि आपकी monthly income का कितना हिस्सा existing और proposed EMIs में चला जाएगा।
CIBIL के अनुसार, यदि total EMIs monthly salary के 50% से ज्यादा हो जाएं तो loan approval की संभावना कम हो सकती है।
हालांकि actual threshold lender, loan type और borrower profile के अनुसार अलग हो सकता है।
5. Job और Business Stability
Bank के लिए repayment capacity के साथ income की stability भी महत्वपूर्ण है।
Salaried applicant के मामले में lender employment history और income continuity देख सकता है।
Business owners और self-employed borrowers के लिए business vintage, income records, bank statements, GST/ITR और अन्य financial documents महत्वपूर्ण हो सकते हैं।
CIBIL भी employment status और steady income को loan evaluation के factors में शामिल करता है।
6. Repayment History
आपने पुराने loans और credit cards की EMI समय पर चुकाई है या नहीं, इसका असर future borrowing पर पड़ सकता है।
Repeated late payments, defaults या overdue amounts credit profile को प्रभावित कर सकते हैं।
इसके उलट, timely repayment एक healthy credit history बनाने में मदद करता है।
7. Loan का प्रकार
Bank loan approval के criteria loan type के अनुसार भी बदलते हैं।
उदाहरण के लिए:
- Home Loan
- Personal Loan
- Auto Loan
- Business Loan
- Education Loan
- Working Capital Loan
हर loan में risk assessment और documentation अलग हो सकता है।
Salary अच्छी है फिर भी Loan क्यों Reject हो सकता है?
कई borrowers सोचते हैं कि अच्छी salary का मतलब automatic approval है। ऐसा नहीं है।
Loan rejection के संभावित कारणों में शामिल हो सकते हैं:
- कमजोर credit history
- existing debt ज्यादा होना
- repayment capacity कम होना
- unstable income
- incomplete documentation
- lender-specific eligibility criteria
- बहुत ज्यादा recent credit applications
इसलिए bank loan approval एक multi-factor assessment है।
Business और MSME Loan में क्या अलग होता है?
MSME और business loans में lender केवल individual salary नहीं देखता। Business की financial health भी महत्वपूर्ण होती है।
Bank/NBFC निम्न documents और indicators देख सकते हैं:
- Business turnover
- Bank statements
- ITR
- GST records
- Profitability
- Existing liabilities
- Cash flow
- Business vintage
- Promoter/borrower credit profile
Business loan में repayment capacity को समझने के लिए cash flow विशेष रूप से महत्वपूर्ण हो सकता है।
Loan Approval के लिए क्या करें?
बेहतर credit profile बनाए रखें
EMI और credit-card bills समय पर pay करें।
Existing debt को control करें
नई borrowing से पहले अपनी existing EMI obligations देखें।
Documents ready रखें
Income proof, bank statements, identity documents और अन्य required records updated रखें।
बार-बार loan applications से बचें
Short period में कई credit applications आपकी credit profile पर enquiries बढ़ा सकती हैं।
अपनी repayment capacity समझें
सिर्फ maximum eligible amount देखकर loan न लें। Monthly cash flow के हिसाब से EMI तय करना महत्वपूर्ण है।
Bank Loan Approval का आसान गणित
सरल भाषा में bank यह समझना चाहता है:
Income → Existing Obligations → Credit History → Repayment Capacity → Risk → Loan Decision
यानी सिर्फ यह सवाल नहीं होता कि “आप कितना कमाते हैं?”
बल्कि सवाल यह भी होता है:
“आपके पास loan चुकाने के बाद कितनी repayment capacity बचेगी?”
निष्कर्ष
Bank loan approval कई financial और personal factors के combination पर निर्भर करता है। Salary महत्वपूर्ण है, लेकिन CIBIL score, repayment history, existing loans, EMI burden और income stability भी equally relevant हो सकते हैं।
इसलिए loan लेने से पहले अपने credit report, existing liabilities और monthly cash flow को समझना बेहतर financial planning का हिस्सा है।
FAQs
Q1. क्या ज्यादा salary से loan आसानी से मिल जाता है?
जरूरी नहीं। Salary के साथ credit history, existing debt और repayment capacity भी देखी जाती है।
Q2. Loan के लिए अच्छा CIBIL score क्यों जरूरी है?
CIBIL Score और report lender को आपकी credit history और repayment behaviour समझने में मदद करते हैं।
Q3. Existing loan होने से नया loan reject हो सकता है?
हो सकता है, खासकर यदि existing EMIs आपकी repayment capacity पर ज्यादा दबाव डाल रही हों।
Q4. Bank EMI-to-income ratio क्यों देखता है?
इससे lender यह assess करता है कि आपकी income के मुकाबले debt obligations कितनी हैं।
Q5. Business loan में क्या देखा जाता है?
Business income, cash flow, turnover, existing liabilities, financial records और borrower/promoter की credit profile जैसे factors महत्वपूर्ण हो सकते हैं।